 Business · News 61
I nflation rose to 3.1 per cent in August, and the average Brit could still be forgiven for rolling their eyes and saying: “Tell us something we don’t know.” Inevitably the villain of the piece was energy, and the continuing closure of that narrow waterway in the Persian Gulf we are by now all too familiar with. That would be the Strait of Hormuz. Whether it’s diesel, heating oil, petrol at the pumps, or transport, the price of which is heavily influenced by the price of fuel, it doesn’t much matter.
They combined to add heat to the prices we pay and to the severe headache facing Andy Burnham and his government . Some put upon junior civil servant was doubtless dispatched to the nearest Boots to pick up a job lot of paracetamol. But wait just a minute.
I have some good news for you, because it isn’t quite as bad as it looks. At least not yet. Delve into the Office For National Statistics missive and you will find that core inflation, which excludes the most volatile categories including energy, food, booze and tobacco, wasn’t so nasty.
The measure is designed to show the “underlying” level of inflation in the economy, since food and energy prices can rocket around like crazy due to a drought or a foreign war. While those are still important factors to consider, they often muddy the picture of how an economy is actually doing. By stripping out the choppy bits, we get a better idea.
As a measure of danger to an economy, it’s a bit like ignoring the size of waves around a boat and instead focusing on its direction and speed. The Bank of England’s rate setting Monetary Policy Committee (MPC) can’t do much about energy prices because it can’t do anything about the causes of the surge: Donald Trump, the Iranians, and/or the Houthis in Yemen . It has even less power, if that’s possible, to influence El Niño, and the impact the latter might have on food prices down the line .
It thus makes sense to have a measure that gauges what’s happening with those things it can use monetary policy to influence. That, more or less, is what core inflation is comprised of and it has held steady for the last four months at 2.6 per cent. That is still too high for comfort, certainly for the more hawkish members of the MPC, given the 2 per cent target they are working towards.
But its relative stability amid the current chaos is nonetheless comforting. It suggests the UK is on a sensible course. It may also be enough to stave off an interest rate rise tomorrow, something the economy can ill afford despite the resilience it has shown.
Service price inflation, doggedly high for an extended period of time, had hit 3.7 per cent in May but has since come back to 3.4 per cent, where it has stayed. Again, too high, but at least stable. Nor has there been any sign of the wage-price spiral that givens the entire membership of the MPC sleepless nights.
To the contrary. The latest data from the ONS showed average wage growth falling to 3.9 per cent from 4.2 per cent . Private sector pay is now under water when compared to headline inflation at 2.9 per cent.
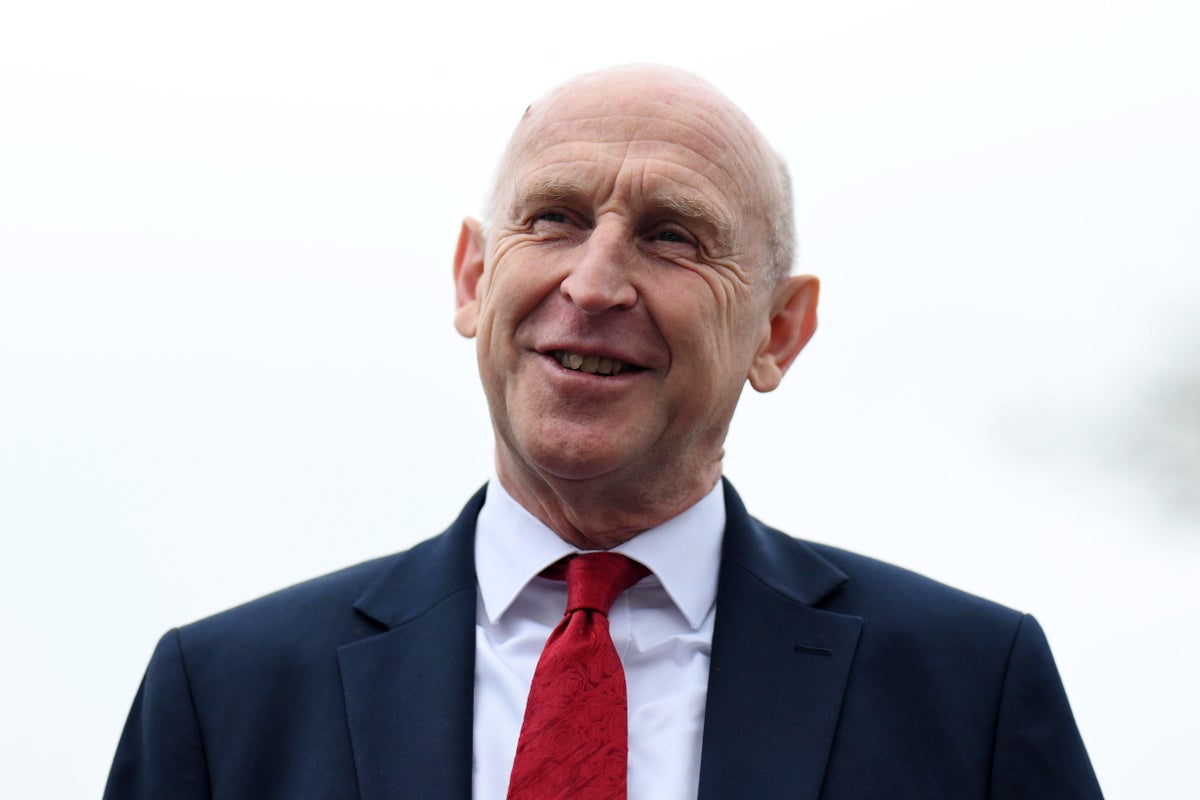
This is, obviously, no fun for those of us toiling at the coal face. It is also a big problem for Mr Burnham and Chancellor John Healey. That toxic phrase “cost of living crisis” just won’t go away .
Any attempt to hike the consumer’s taxes will thus be politically poisonous, which is why we’re hearing so much about easier targets, such as gaming machines, in the run up to the Budget. However, while you and I might be gnashing our teeth when we compare our pay slips to our bills, the MPC will be quietly pleased. The fly in the ointment of this my rosy assessment come courtesy of the City of London, where the markets don’t think it will last.
They could easily be wrong. They often are. But that doesn’t much matter for those at the whim of their views.
That would be people seeking mortgages. The markets don’t believe the doves on the MPC will be able to hold the line for long. They fear that those energy price increases will slop over into other sectors, pushing core inflation higher and forcing the Bank’s hand.
The prices of the fixed rate mortgage deals most people prefer are based not on where base rates are today (3.75 per cent) but on the City’s longer term expectations for where they might go. At one point, it was predicting as many as five rate rises. It is still pricing in four.
These fears are, to my mind, over done. But lenders don’t take their cue from me. As I write, an email has just arrived from Nicholas Mendes, at mortgage broker John Charcol, highlighting price increases from a slew of lenders.
NatWest, Skipton Building Society, Coventry Building Society, TSB and the Principality Building Society have all pushed the button. Others will follow. Borrowers need to move fast.
Get the paperwork signed and the offer locked in. Most lenders will honour them when they are made, even if prices rise the next day. The cost of delay could be appallingly high.
Source: The Independent